Venture debt term sheets often arrive looking more fixed than they actually are. Founders — particularly first-time founders, or those focused on the relief of securing capital at all — sometimes treat the initial terms as close to non-negotiable, when in practice there’s often more room to improve a deal than the first offer suggests. Here are five mistakes that show up repeatedly.
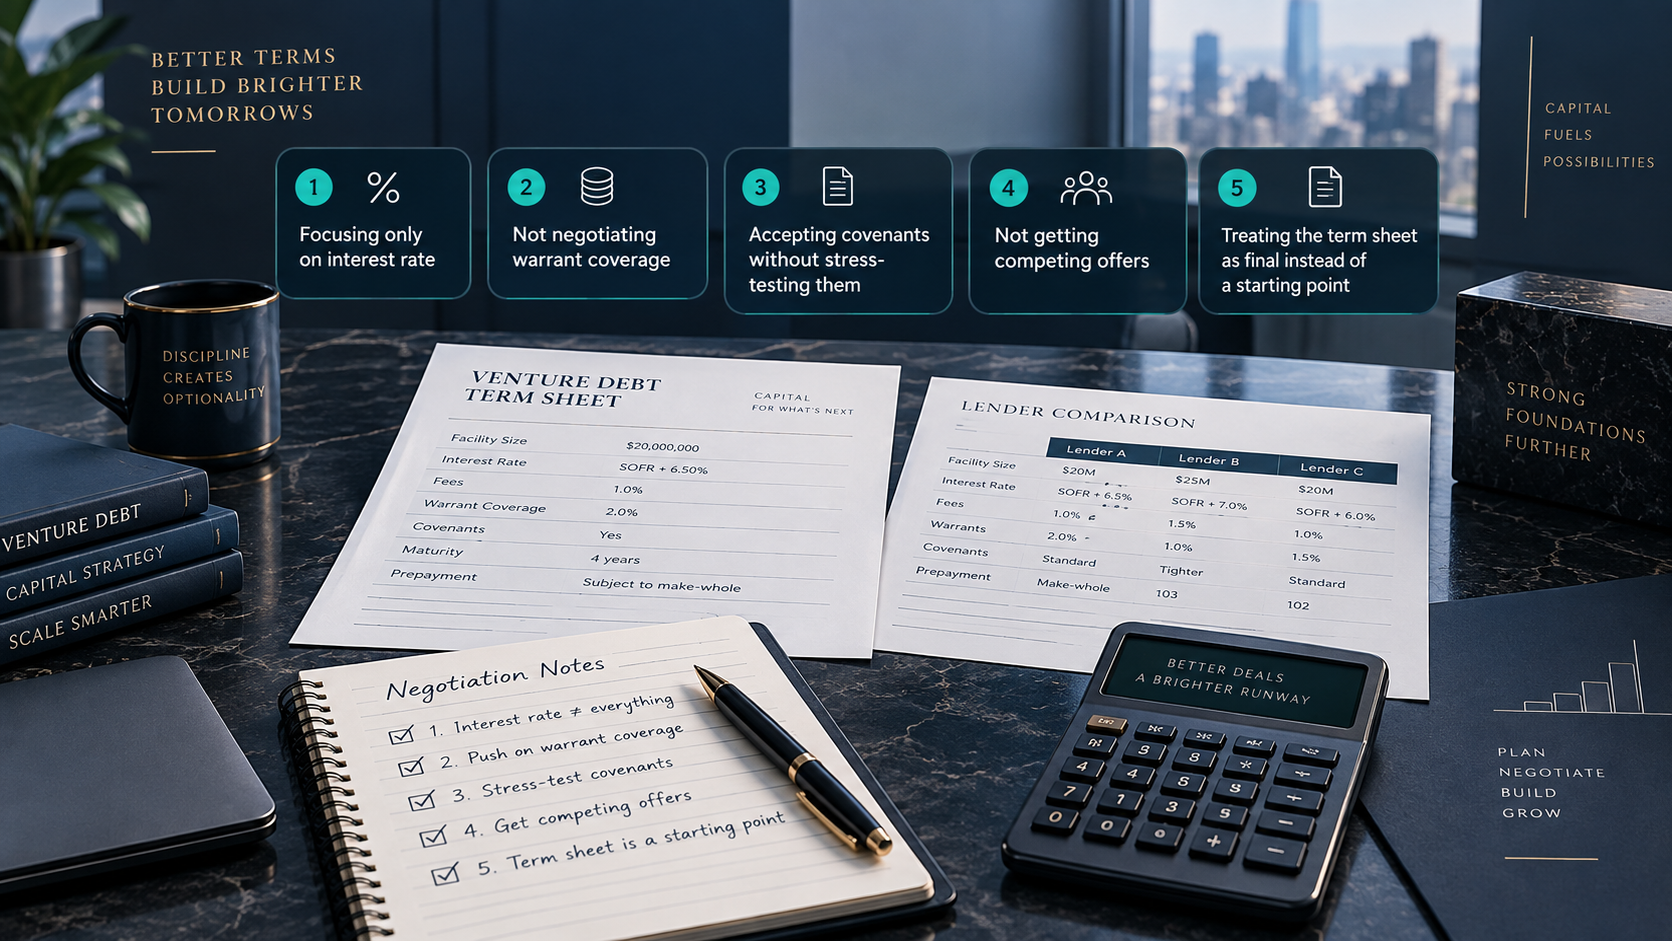
Mistake 1: Focusing only on the interest rate
The interest rate is the easiest term to compare across offers, which is exactly why it gets disproportionate attention. But warrant coverage, covenant structure, the length of the interest-only period, and prepayment terms can all matter as much or more to your company’s actual outcome than a modest difference in rate. A founder who negotiates hard on rate but accepts unfavorable terms everywhere else has likely made a worse deal overall than one who negotiated more broadly across the full term sheet.
Mistake 2: Not negotiating warrant coverage
Warrants are often treated as a fixed, standard part of a venture debt deal — but warrant coverage varies meaningfully between lenders and is frequently negotiable, particularly for companies with strong metrics or competing offers in hand. Since warrants represent real future dilution, even though they don’t appear as a cash cost today, treating them as non-negotiable by default is a missed opportunity in many deals.
Mistake 3: Accepting covenants without stress-testing them
Covenants — minimum cash balances, revenue thresholds, and similar conditions — are often reviewed against a company’s current plan, which almost always clears them comfortably. The mistake is not stress-testing those same covenants against a more conservative, below-plan scenario. A covenant that looks perfectly reasonable today can become a real problem if growth slows even moderately, and founders who don’t model this before signing sometimes find themselves in a difficult conversation with their lender later.
Mistake 4: Not getting competing offers before negotiating
It’s difficult to know whether a specific term is reasonable or aggressive without a second offer to compare it against. Founders who negotiate against a single term sheet, without a genuine alternative in hand, typically have less leverage than those who do — even if they never intend to switch lenders, having a real competing offer changes the tenor of the negotiation and often improves the terms available.
Mistake 5: Treating the term sheet as final rather than as a starting point
Many founders — especially those without prior experience raising debt — assume a term sheet from an institutional lender is close to fixed, when in practice the initial terms often leave room for negotiation, particularly around the specific points above. Approaching a term sheet as an opening position rather than a final answer, and asking directly what’s negotiable, frequently produces a better outcome than accepting it as presented.
Why these mistakes are more consequential than they first appear
Venture debt is a multi-year commitment, and the terms you accept shape your company’s flexibility and cost structure well beyond the moment of signing. A founder who treats the negotiation as a formality to get through quickly, rather than a genuine opportunity to shape long-term terms, is trading a relatively small amount of upfront effort for a potentially larger, ongoing cost or constraint.
What a stronger negotiation approach looks like in practice
Before entering a venture debt conversation, know your own priorities — is minimizing dilution more important to you than minimizing cash interest cost? Would you trade a slightly higher rate for more favorable covenants? Having genuine competing offers, or at least genuine alternative options, strengthens your position regardless of which specific term you’re negotiating. And treating every major term — not just the rate — as open for discussion tends to produce a meaningfully better overall deal than negotiating narrowly.
FAQ
Is it realistic to negotiate warrant coverage, or is it always fixed by the lender? It varies by lender and by your company’s specific leverage — strong metrics or a competing offer can create real room to negotiate warrant coverage, even though it’s sometimes presented as a fixed policy.
How do I get competing offers without wasting time on options I won’t actually take? Comparing offers through a marketplace that surfaces multiple lenders through a single process is generally more efficient than approaching several lenders separately and repeating the process each time.
Should I involve a lawyer in negotiating a venture debt term sheet? Yes, generally — legal review is a standard and valuable part of the process for any venture debt agreement, given the long-term and legally binding nature of the terms involved.