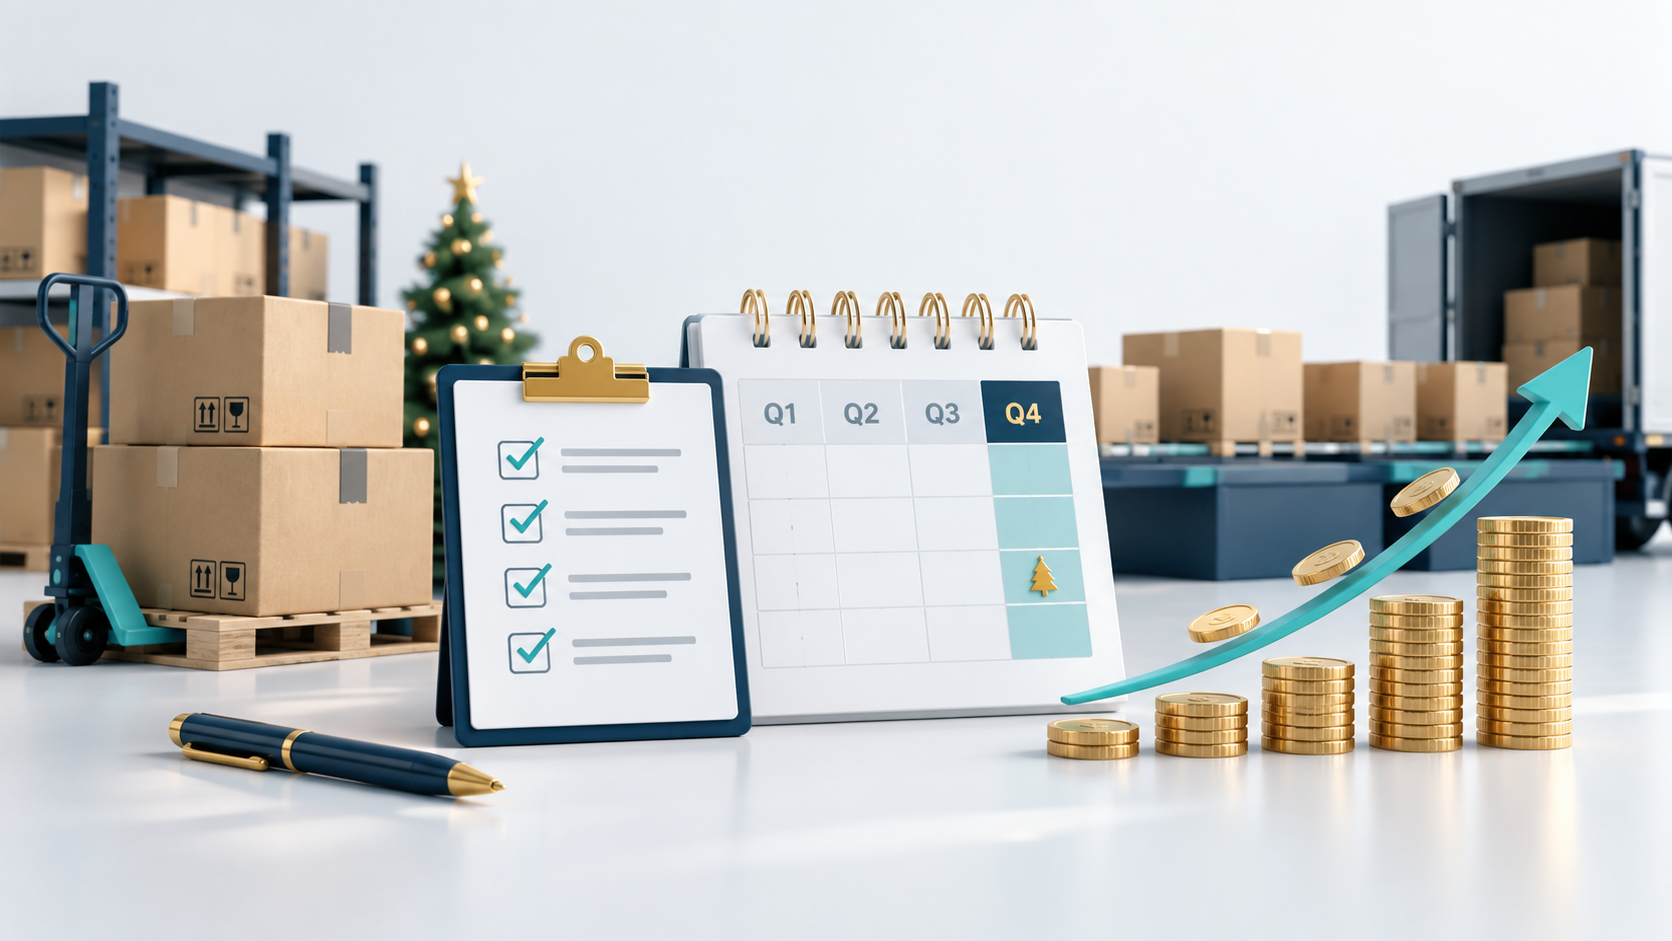
Q4 rewards preparation more than almost any other stretch of the business calendar — and punishes the lack of it just as directly. By the time the holiday rush actually arrives, most of the decisions that determine whether it goes well were already made months earlier. This checklist is built around the cash flow side of that preparation specifically, since it’s the piece most likely to be underestimated until it’s suddenly urgent.
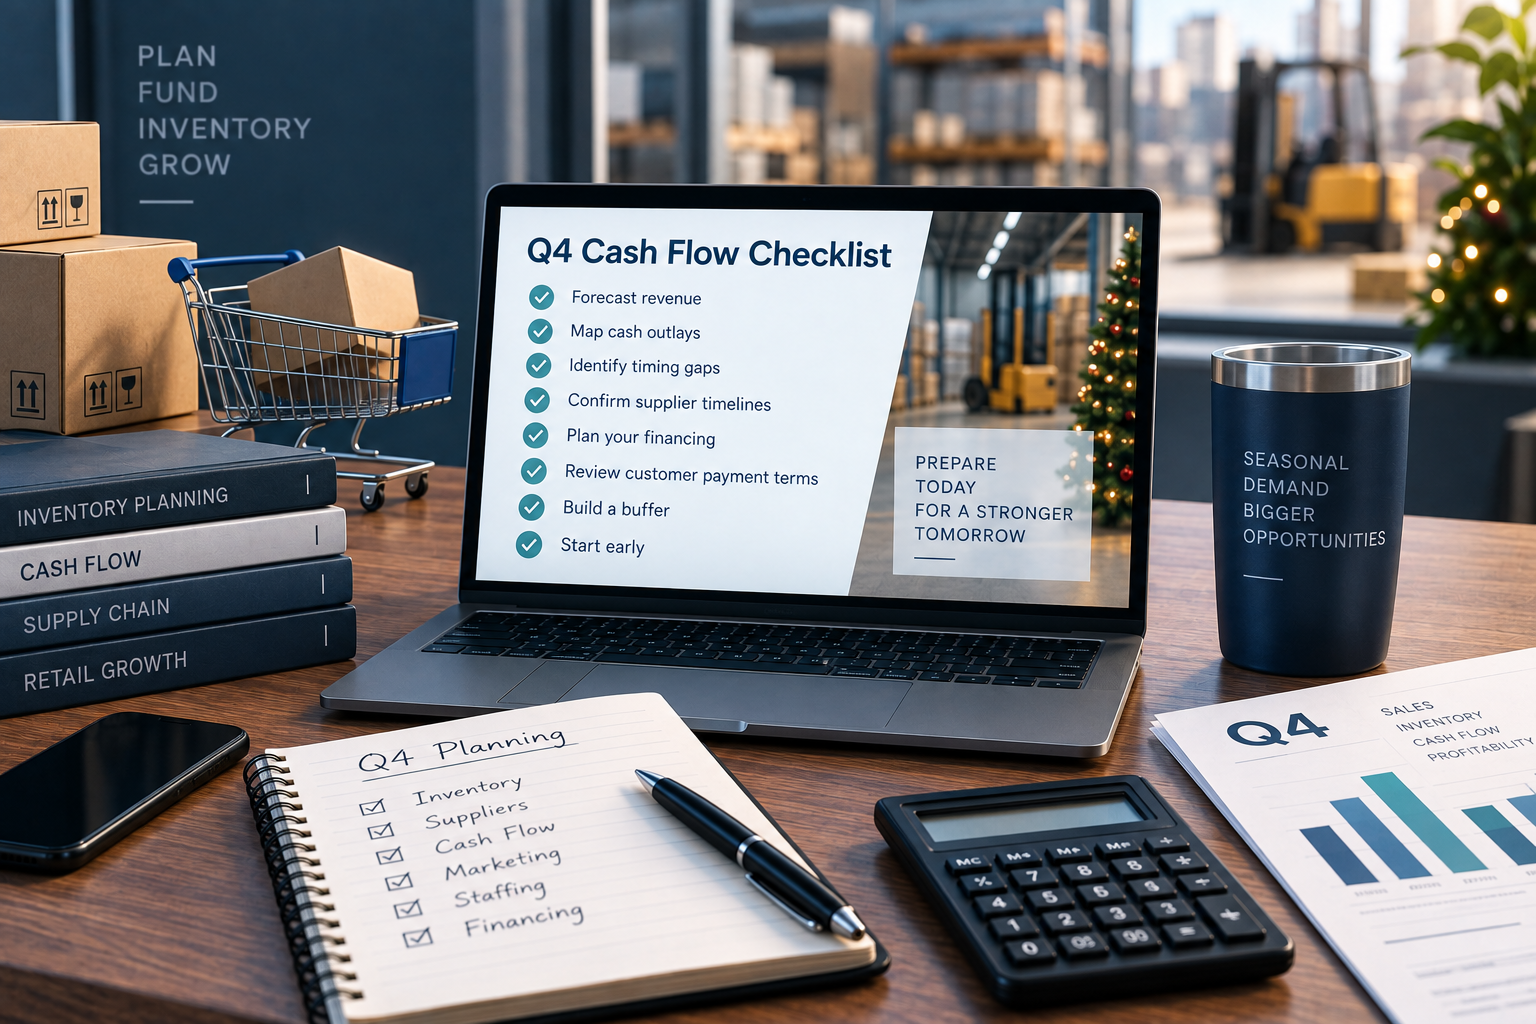
1. Forecast your Q4 revenue realistically, not optimistically
Start with a grounded projection based on last year’s actual performance, adjusted for any known changes — new accounts, discontinued products, shifts in your customer base. An overly optimistic forecast leads to over-ordering and cash strain; an overly conservative one leads to stockouts during your highest-demand period. Neither extreme serves you well, so build the forecast from real data rather than hope or worst-case caution.
2. Map the cash outlay required to hit that forecast
Once you have a revenue target, work out what it actually costs to be ready for it: inventory purchases, any seasonal staffing, additional shipping or fulfillment costs, and marketing spend tied to the season. This is the number that matters most for financing planning — not your expected Q4 revenue, but the cash you need before that revenue arrives.
3. Identify the gap between when cash goes out and when it comes back in
For most retail and distribution businesses, the cash outlay for Q4 happens well before the Q4 revenue does — inventory is purchased and paid for in the summer or early fall, while the bulk of sales revenue doesn’t arrive until the season itself. Quantifying this gap in real dollar terms, not just acknowledging it exists, is what turns this into an actionable financing conversation rather than a vague sense of seasonal stress.
4. Confirm supplier and shipping lead times in writing
Q4 is a high-demand period for suppliers and freight capacity across nearly every industry. Confirming actual, current lead times — not last year’s — avoids discovering a timeline problem after financing and ordering decisions have already been made.
5. Decide how the cash flow gap will actually be funded
Once you know the size and timing of the gap, decide deliberately how it will be covered — existing cash reserves, a line of credit, PO financing for the inventory buildup specifically, or some combination. The point of doing this deliberately, rather than defaulting to whatever’s easiest in the moment, is that different funding sources have different lead times of their own, and starting that process early avoids compounding a supplier timeline problem with a financing timeline problem.
6. Revisit your payment terms with major customers
If you extend payment terms to retail or wholesale customers, understand how those terms will interact with your own cash flow during and after Q4 — a strong sales season doesn’t help your cash position if the resulting revenue is tied up in 60-day receivables well into the next year. This is a good moment to revisit whether invoice financing should be part of your plan for post-season receivables, not just pre-season inventory.
7. Build in a buffer for the unexpected
Q4 plans rarely go exactly as forecast — a popular item may sell out faster than expected, a supplier delay may compress your timeline, or a marketing push may outperform projections in a way that creates its own inventory pressure. Building a modest cash or credit buffer beyond your baseline plan gives you room to respond to these situations without them becoming crises.
8. Start this process earlier than feels necessary
The single most common Q4 planning mistake isn’t getting any individual step wrong — it’s starting the whole process too late, once the pressure of the season is already visible rather than while there’s still comfortable lead time to act. If you’re doing this exercise for the first time in September or October, you’re already working with a compressed timeline relative to a business that started in the summer.
FAQ
How far in advance should Q4 cash flow planning actually start? For most retail and distribution businesses, planning is ideally underway by mid-summer, since inventory purchasing and financing decisions both typically need to happen well before the season itself.
What if I’m already behind on this planning? It’s still worth working through the checklist as quickly as possible — a compressed timeline is more limiting than an early one, but a late start is still better than no deliberate planning at all.
Should PO financing and a working capital line of credit be treated as competing options? Not necessarily — many businesses use both for different parts of the cycle: PO financing for the specific inventory buildup, and a working capital line for the broader operational flexibility around the season.