Covenants are one of those venture debt terms that get a quick mention during negotiation and then rarely get revisited until, potentially, they become an urgent problem. Understanding what they actually require — and what genuinely happens if your company falls short of one — matters more than the brief attention they usually get in a term sheet conversation.
What a covenant actually is
A covenant is a condition your company agrees to maintain throughout the life of the loan — common examples include a minimum cash balance, a minimum revenue threshold, or a maximum burn rate. Covenants exist to give the lender an early signal if the business is deteriorating, well before a full default would otherwise become apparent, and they’re a standard, expected part of most venture debt agreements.
Types of covenants you’re likely to encounter
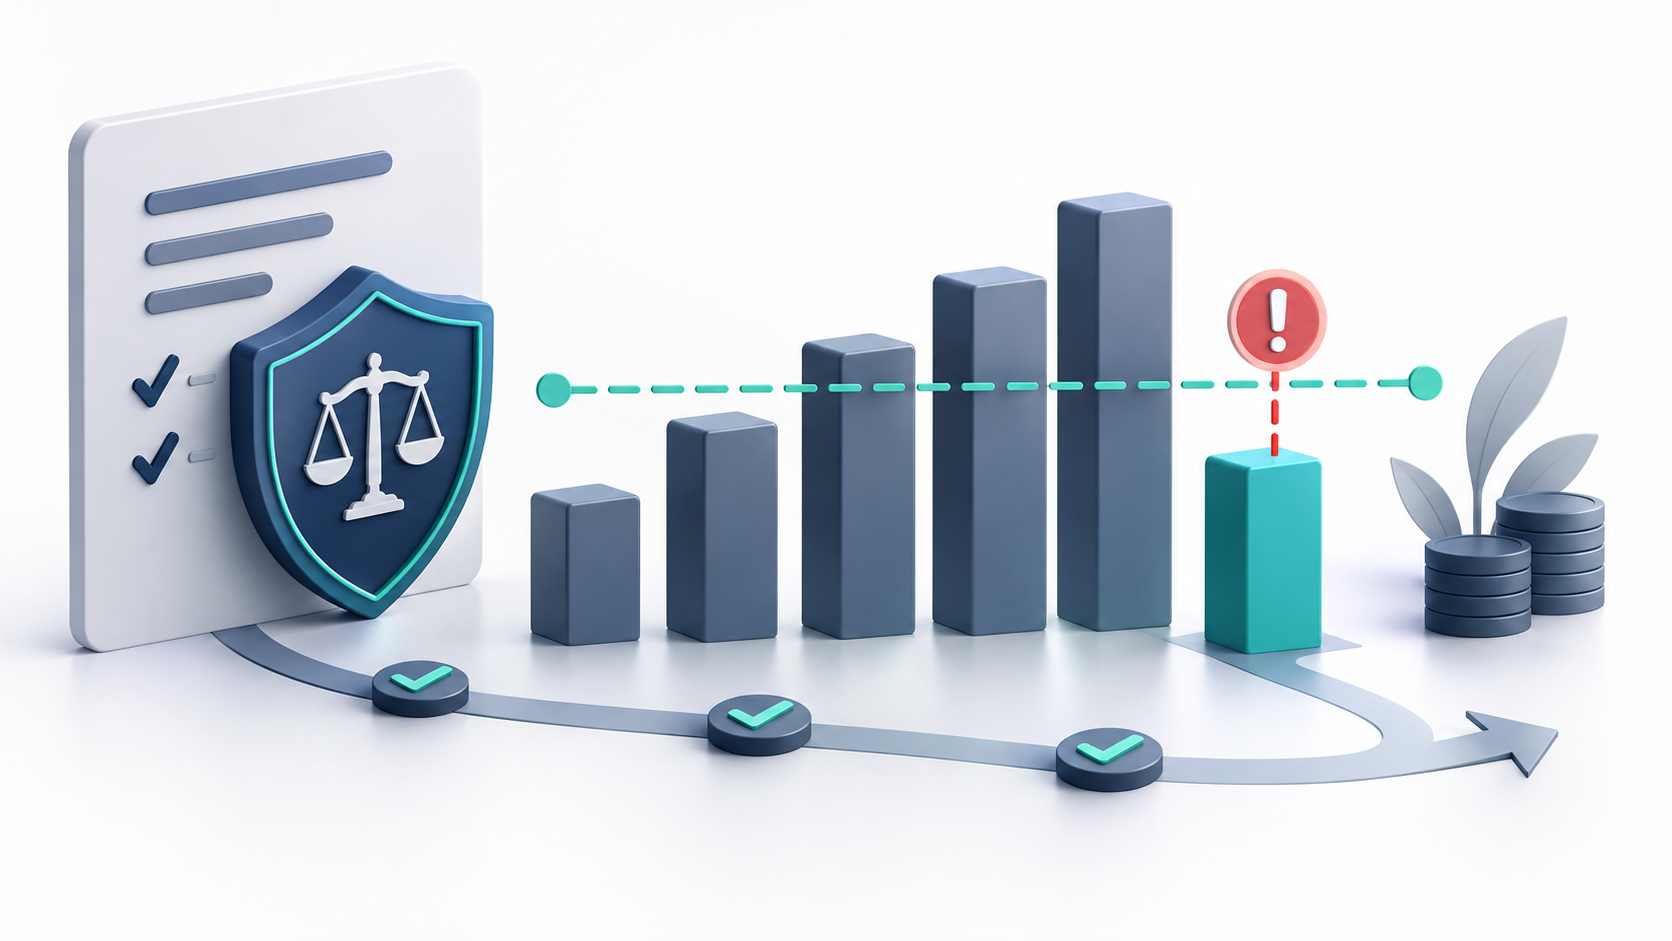
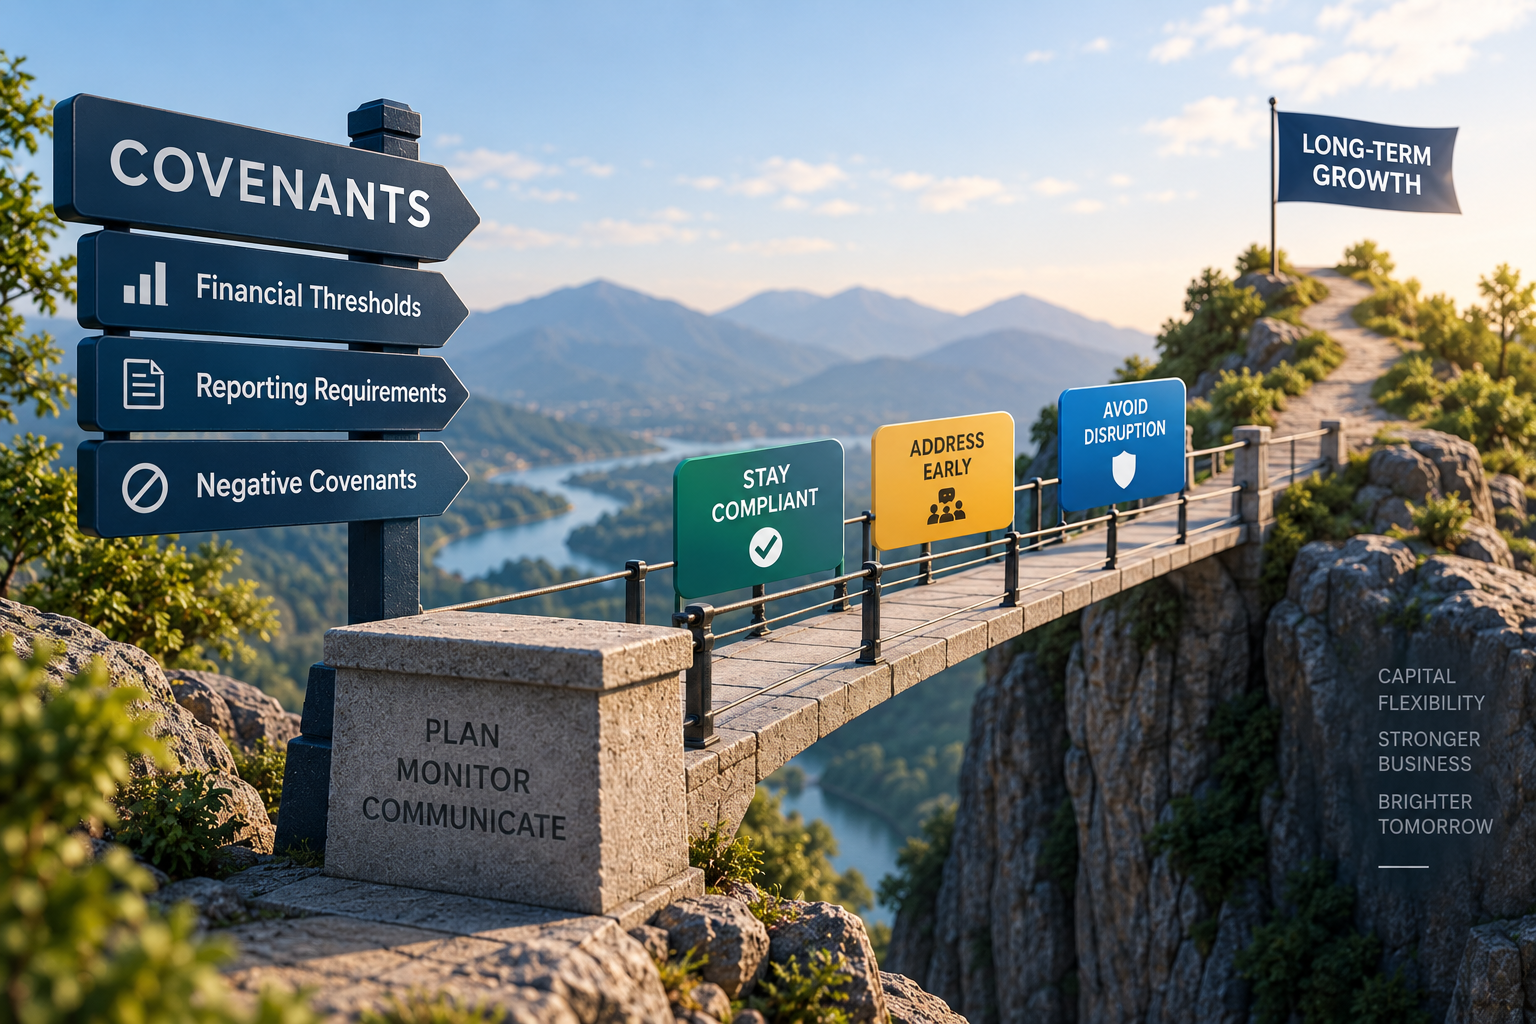
Financial covenants set specific numerical thresholds — minimum cash on hand, minimum revenue, or a maximum expense level relative to revenue. These are the most common and the most important to stress-test against a realistic, not optimistic, view of your company’s trajectory.
Reporting covenants require you to provide regular financial information to the lender — monthly or quarterly financials, cash balance updates, or similar reporting. These don’t carry the same risk of default as financial covenants but do create an ongoing administrative obligation worth understanding upfront.
Negative covenants restrict certain actions without the lender’s consent — taking on additional debt, making a large acquisition, or other significant changes to the business. These matter less day-to-day but can become relevant if your company’s plans shift in ways that weren’t anticipated when the covenant was negotiated.
What actually happens if you breach a covenant
This varies significantly by agreement, which is exactly why it’s worth understanding your specific terms rather than assuming a universal outcome. Some agreements include a cure period — a window of time to fix the issue before it’s treated as a formal default. Some breaches trigger a conversation and renegotiation rather than an immediate consequence, particularly if the lender has an ongoing relationship and confidence in the company’s broader trajectory. In more serious cases, a breach can allow the lender to accelerate the loan, demanding immediate repayment of the full remaining balance.
Why the relationship with your lender matters here
In practice, many covenant breaches are resolved through direct conversation rather than the most severe contractual remedy available. A lender with an ongoing, transparent relationship with your company — one where you’ve proactively flagged a likely issue before it happens, rather than after — is generally more willing to work through a covenant issue constructively than one blindsided by a breach they learn about only when it’s already occurred.
How to avoid being surprised by a covenant breach
Model your covenants against a conservative scenario, not just your operating plan. A covenant that looks comfortably clear under your current plan can become a real risk if growth slows or an expense runs higher than expected — worth checking explicitly before signing, not after a slow quarter arrives.
Monitor covenant compliance regularly, not just at reporting deadlines. Waiting until a quarterly report to discover a covenant issue removes your ability to address it proactively. Tracking covenant-relevant metrics on an ongoing basis gives you time to react before a breach becomes unavoidable.
Communicate early if you see a likely issue coming. Flagging a probable covenant issue to your lender in advance, along with your plan to address it, is almost always better received than a breach that arrives as a surprise.
Are covenants negotiable?
Often, yes, at least to some degree — the specific thresholds, the length of any cure period, and the consequences of a breach can sometimes be negotiated, particularly for companies with strong metrics or a competing offer in hand. Treating covenants as a fixed, non-negotiable part of the term sheet is a common mistake worth avoiding.
FAQ
Do all venture debt agreements include covenants? Most do, though the specific type and strictness vary significantly by lender and by the company’s stage and metrics — worth reviewing carefully rather than assuming a standard set of terms applies universally.
Can a single covenant breach end my relationship with a lender? Not necessarily — many breaches are resolved through conversation and renegotiation, particularly for companies with an otherwise strong relationship and trajectory, though the specific outcome depends on your agreement and the severity of the breach.
Should I have a lawyer review covenant terms before signing? Yes, generally — covenants have real legal and financial consequences, and legal review is a standard part of evaluating any venture debt agreement.