If your business carries both significant receivables and significant inventory, you might assume a lender would treat a dollar of one roughly the same as a dollar of the other when structuring an asset-based facility. In practice, lenders rarely do — and understanding why can help you anticipate your terms, and in some cases, structure your business’s own working capital cycle to your advantage.
Why receivables are generally viewed more favorably
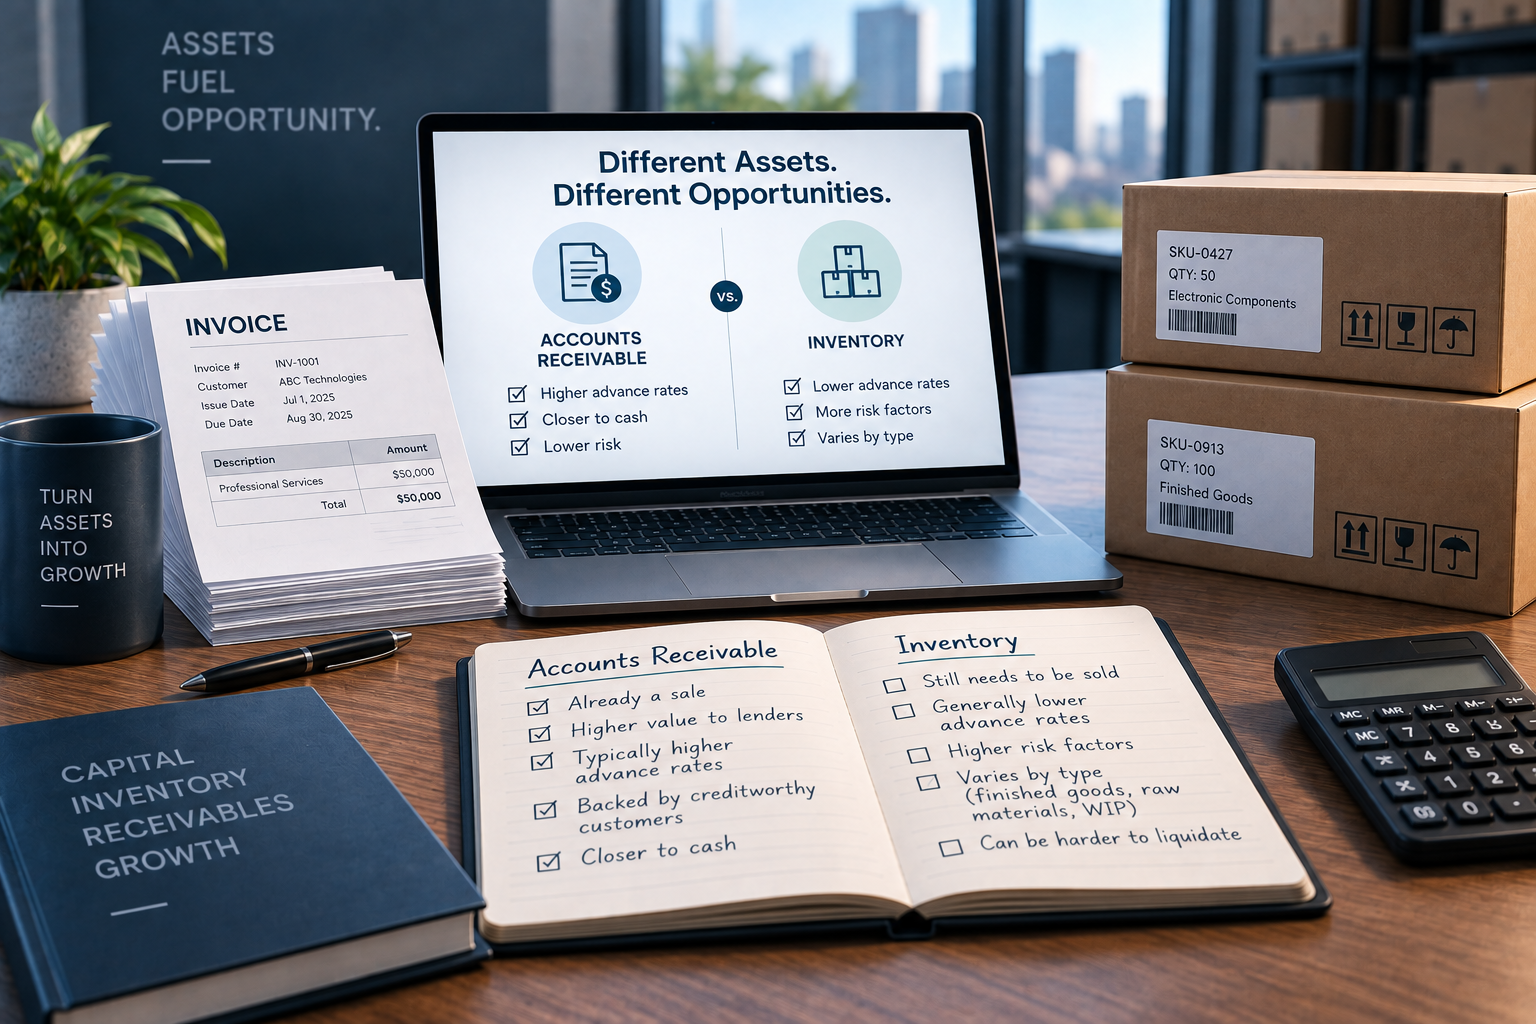
An outstanding invoice from a creditworthy customer is, in a very real sense, already a sale — the product or service has been delivered, and what remains is simply the passage of time until payment arrives. That makes receivables closer to cash than almost any other type of collateral, which is exactly why lenders typically advance a higher percentage of receivables value than they do for other asset types. The primary risk a lender is pricing in is whether the customer actually pays, not whether the underlying asset can be sold for a reasonable price.
Why inventory carries more risk from a lender’s perspective
Inventory, by contrast, still has to be sold before it becomes cash — and that process carries several layers of uncertainty a receivable doesn’t. Will it sell at the expected price? How quickly? What if it becomes obsolete, damaged, or simply falls out of demand before it moves? Because a lender needs to consider what would happen if they had to liquidate the inventory themselves in a worst-case scenario, they typically advance a meaningfully lower percentage of inventory value than receivables value.
Not all inventory is treated the same, either
Within inventory itself, there’s a real hierarchy. Finished goods that are ready to sell are generally viewed more favorably than raw materials or work-in-progress, since finished goods are closer to becoming a completed, revenue-generating sale. Fast-moving, broadly resellable inventory is viewed more favorably than highly specialized, seasonal, or perishable inventory that would be difficult to liquidate quickly if needed. Two businesses with identical total inventory value can receive very different advance rates depending on the composition and liquidity of what’s actually on their shelves.
What this means practically for your borrowing capacity
If your business carries a mix of both asset types, understanding this hierarchy helps you anticipate roughly how a lender will value your overall asset base — and can highlight where you have more untapped borrowing capacity than you might assume. A business with substantial, well-aged receivables from creditworthy customers may have more available credit hiding in that side of the balance sheet than in an equivalent dollar amount of inventory.
Can you influence which asset type dominates your collateral base?
Not usually in the short term, since your asset mix reflects how your business actually operates — a wholesale distributor will naturally carry more inventory, while a service-based B2B company will naturally carry more receivables. But understanding this dynamic is still useful when negotiating terms, timing a financing request, or deciding how aggressively to extend payment terms to customers (which increases receivables) versus how much inventory to carry at any given time.
A specific scenario worth understanding
A business that shifts toward net terms with customers, extending 30 or 60-day payment windows rather than requiring payment on delivery, increases its receivables balance — which, from a collateral perspective, can actually strengthen an asset-based facility, even though the immediate cash flow impact of longer customer terms feels like a negative on its own. This is a useful, if slightly counterintuitive, example of how these dynamics interact in practice.
What to ask a lender directly
Rather than assuming a general advance rate applies to your situation, ask directly what percentage your specific lender would advance against your actual receivables aging and your specific inventory composition. Two lenders can have meaningfully different advance rate policies, and the difference between them can represent a significant amount of available capital for an asset-heavy business.
FAQ
If most of my collateral is inventory, does that mean I’ll get worse terms overall? Not necessarily worse terms, but likely a lower advance rate against that specific portion of your collateral compared to what receivables would receive — worth understanding clearly rather than assuming a flat rate applies across your whole asset base.
Can I improve my inventory’s advance rate? Factors like inventory turnover, the mix of finished goods versus raw materials, and how easily the inventory could be resold all influence advance rates — some of which may be within your control depending on how you manage production and stock levels.
Does the age of my receivables affect their advance rate? Yes — current receivables are generally advanced at a higher rate than past-due ones, since the likelihood of collection declines the longer an invoice remains unpaid.