Using revenue-based financing to fund a marketing push has an obvious appeal: the campaign is supposed to generate revenue, and the financing repays itself from that same revenue. It’s a clean, intuitive story. But “the math conceptually works” and “the math actually works for your specific numbers” are different questions, and only one of them should determine whether you move forward.
Why marketing spend is a natural, but not automatic, fit
Revenue-based financing works best when there’s a reasonably direct, calculable line between the capital deployed and the revenue it generates. Marketing spend can absolutely fit that pattern — but only when you have a real, historically grounded understanding of your return on that spend. A business with a well-established customer acquisition cost and lifetime value has the data to make this evaluation honestly. A business without that data is essentially guessing, and financing a guess with borrowed capital carries real risk.
The calculation that actually matters
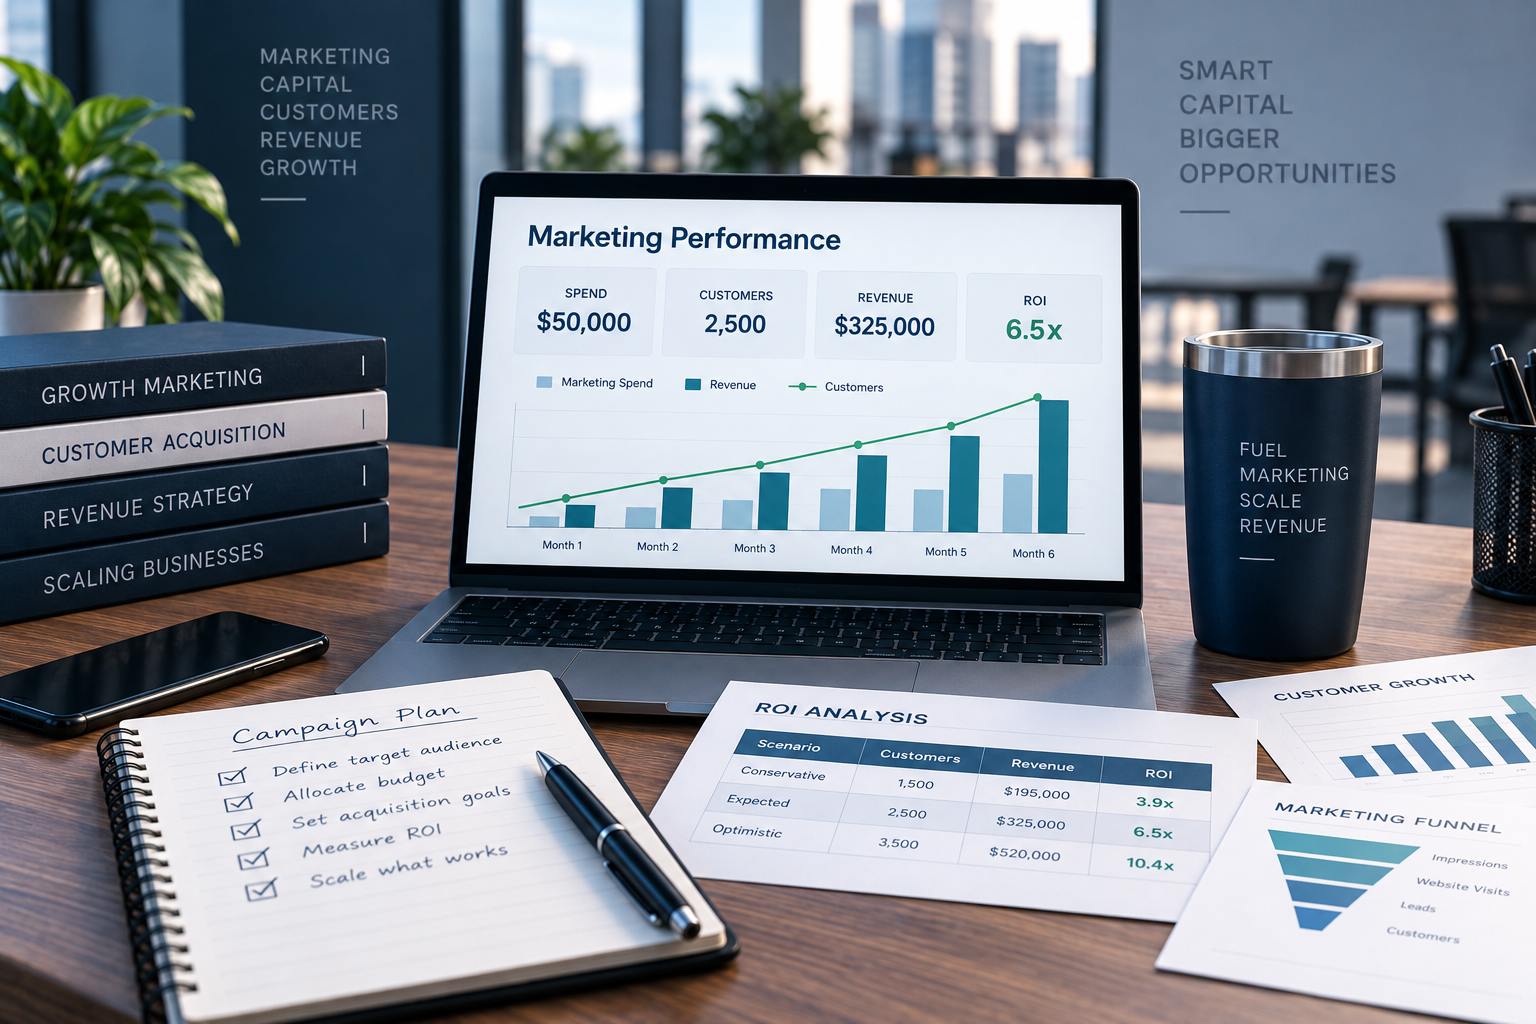
Before committing, calculate: what is your realistic customer acquisition cost at the scale you’re planning to spend (which may differ from your cost at current, smaller spend levels), what is the expected lifetime value or near-term revenue from those customers, and over what timeline does that revenue actually materialize? Compare that timeline and return against the specific repayment terms of the financing — not in the abstract, but with your actual numbers plugged in.
Why scale matters more than people expect
Marketing performance that looks strong at a modest budget doesn’t always hold up proportionally at a much larger one — channels have limited efficient capacity, and increasing spend can drive up acquisition costs as you move beyond your most responsive audience segments. If you’re using financing to meaningfully scale up spend beyond your current levels, model your expected return at the new spend level specifically, not just extrapolated from your current, smaller-scale performance.
Accounting for the timeline mismatch
Revenue-based financing repayment often begins relatively soon after funding, while the revenue generated by a marketing campaign — particularly one aimed at longer sales cycles or lower-frequency purchases — may take longer to materialize than the repayment schedule assumes. This mismatch doesn’t necessarily rule out using financing for marketing, but it does mean you need cash flow from elsewhere in the business to cover repayment during the gap, rather than assuming the campaign’s revenue will arrive in time to fund its own repayment in real time.
When this approach makes the most sense
You have reliable, historically grounded acquisition metrics — not a rough guess, but real data from prior campaigns at a comparable or reasonably close scale.
The revenue cycle is short enough relative to the repayment timeline that the financing can plausibly be repaid from the campaign’s own results, not purely from unrelated cash flow.
You’re scaling a channel you understand, rather than testing an entirely new, unproven marketing channel with borrowed capital.
When it’s worth more caution
If you’re testing a new channel with no track record, if your acquisition costs at scale are genuinely uncertain, or if the sales cycle for your product is long relative to the repayment timeline, financing the spend with revenue-based capital adds real risk on top of the inherent uncertainty of the marketing performance itself. In these situations, it may be worth testing the channel at a smaller scale with existing cash first, and reserving financing for scaling a channel you’ve already validated.
A practical way to decide
Model three scenarios for your planned campaign: your expected case, a moderately worse case, and a significantly worse case for acquisition cost and conversion. Check whether the financing repayment remains manageable under all three, not just the expected case. If the plan only works when the campaign performs roughly as well as your best historical result, that’s a signal to reconsider the scale of financed spend, not necessarily the decision to use financing at all.
FAQ
Is it ever a bad idea to use revenue-based financing for marketing spend? It can be, specifically when the underlying acquisition and revenue assumptions are unproven or highly uncertain — the financing structure itself isn’t the issue, but financing an unvalidated bet carries more risk than financing a proven, scalable channel.
Should I test a new channel before financing a larger investment in it? Generally, yes — validating performance at a smaller scale with existing cash reduces the risk of committing financed capital to an unproven approach.
How do lenders typically view marketing spend as a use of funds? Lenders generally want to understand your historical acquisition metrics and how confident you are in the return, since this affects both their underwriting and, indirectly, how comfortable you should be with the specific terms offered.