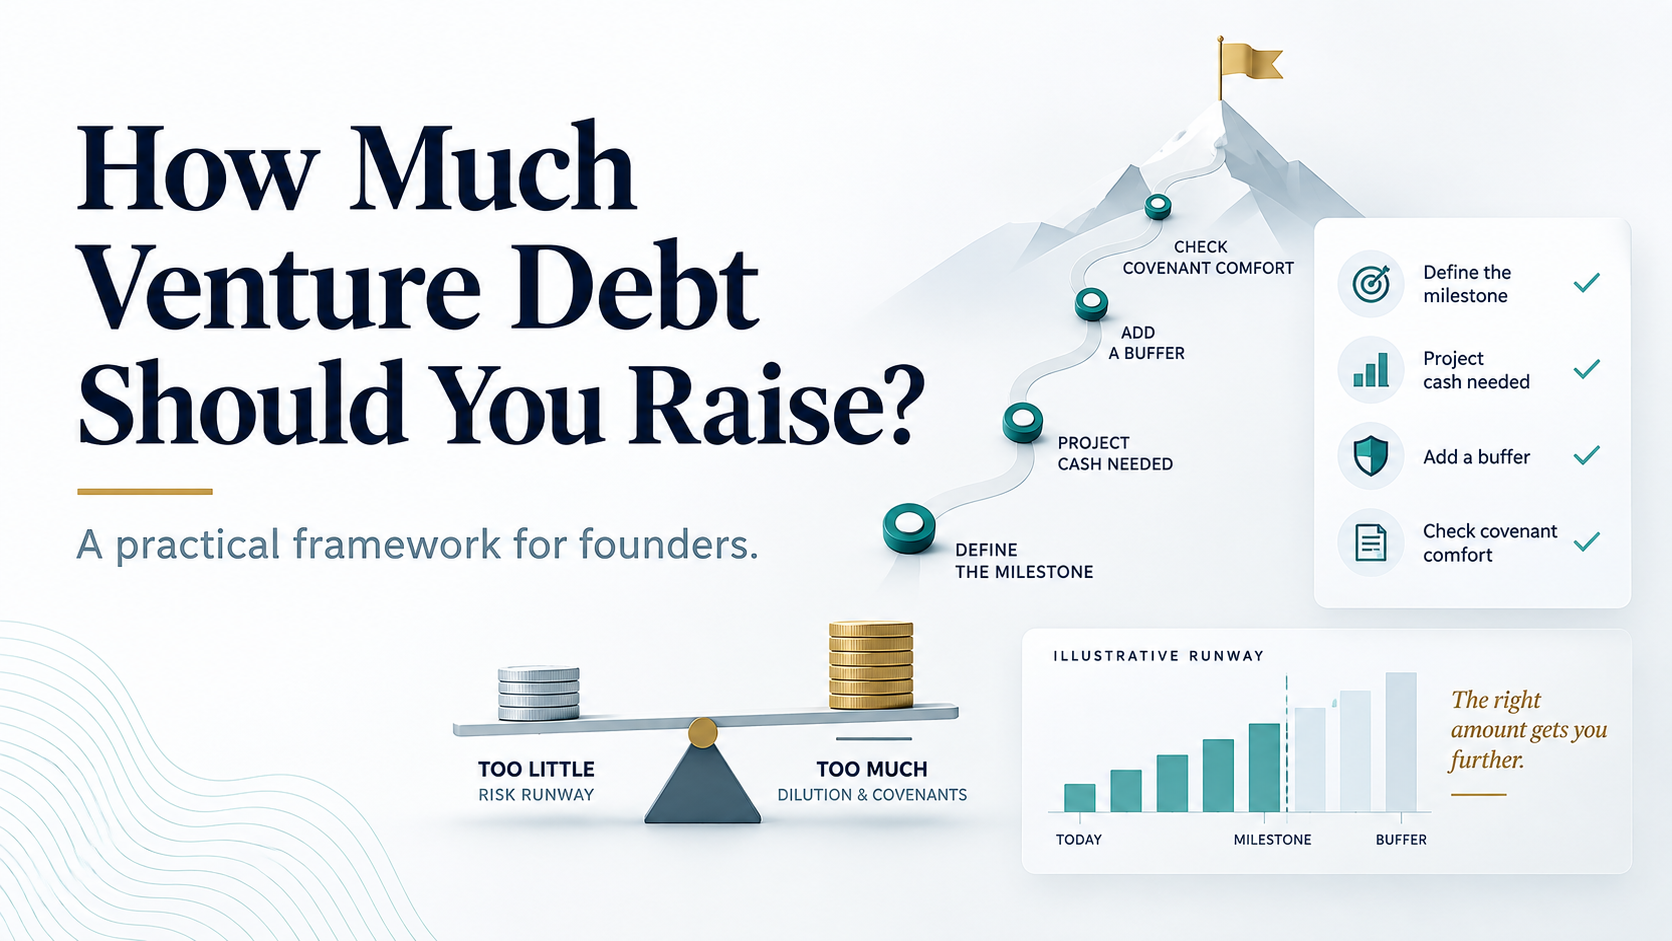
Unlike an equity round, where the amount raised is often shaped by investor appetite and market conditions as much as company need, venture debt gives founders more direct control over sizing the raise to an actual purpose. That control is valuable — but it also means the responsibility for getting the number right sits squarely with you. Raise too little, and you haven’t actually solved the problem you raised debt to solve. Raise too much, and you’re carrying unnecessary cost and covenant exposure for capital you didn’t need.
Start with the specific milestone, not a general cushion
The clearest way to size a venture debt raise is to work backward from a specific milestone: the point at which your company will be in a meaningfully stronger position to raise equity, become cash-flow positive, or otherwise no longer need this capital. Calculate the actual cash required to reach that milestone — not a rough sense of “a bit more runway,” but a real, line-item projection of what it costs to get there.
Build in a realistic buffer, not an optimistic one
Milestones rarely arrive exactly on schedule. A common mistake is sizing a raise against the best-case timeline for hitting a milestone, which leaves no room if things take longer than planned — a near-certainty for most growth-stage companies. A more realistic approach adds a buffer based on how your company’s actual historical timelines have compared to your projections, rather than assuming this time will be different.
Weigh the cost of raising too much against the cost of raising again too soon
Every dollar of venture debt carries some combination of interest cost and, depending on the deal, warrant coverage — so there’s a real cost to raising more than you need. But there’s also a real cost to running out of runway before your next planned raise and having to go back to the market from a weaker position, or under more time pressure than you’d like. This tradeoff doesn’t have a universal right answer — it depends on your company’s specific risk tolerance and how confident you are in your own projections.
Consider what covenants your revenue can comfortably support
Venture debt often comes with covenants — minimum cash balances, revenue thresholds, or similar conditions. The size of the raise affects how comfortably your business can maintain those covenants, particularly in a below-plan scenario. A larger raise with tighter covenants relative to a conservative revenue case can create risk that a smaller, more conservatively sized raise would avoid — worth modeling explicitly rather than assuming the covenants will be fine because your current plan clears them comfortably.
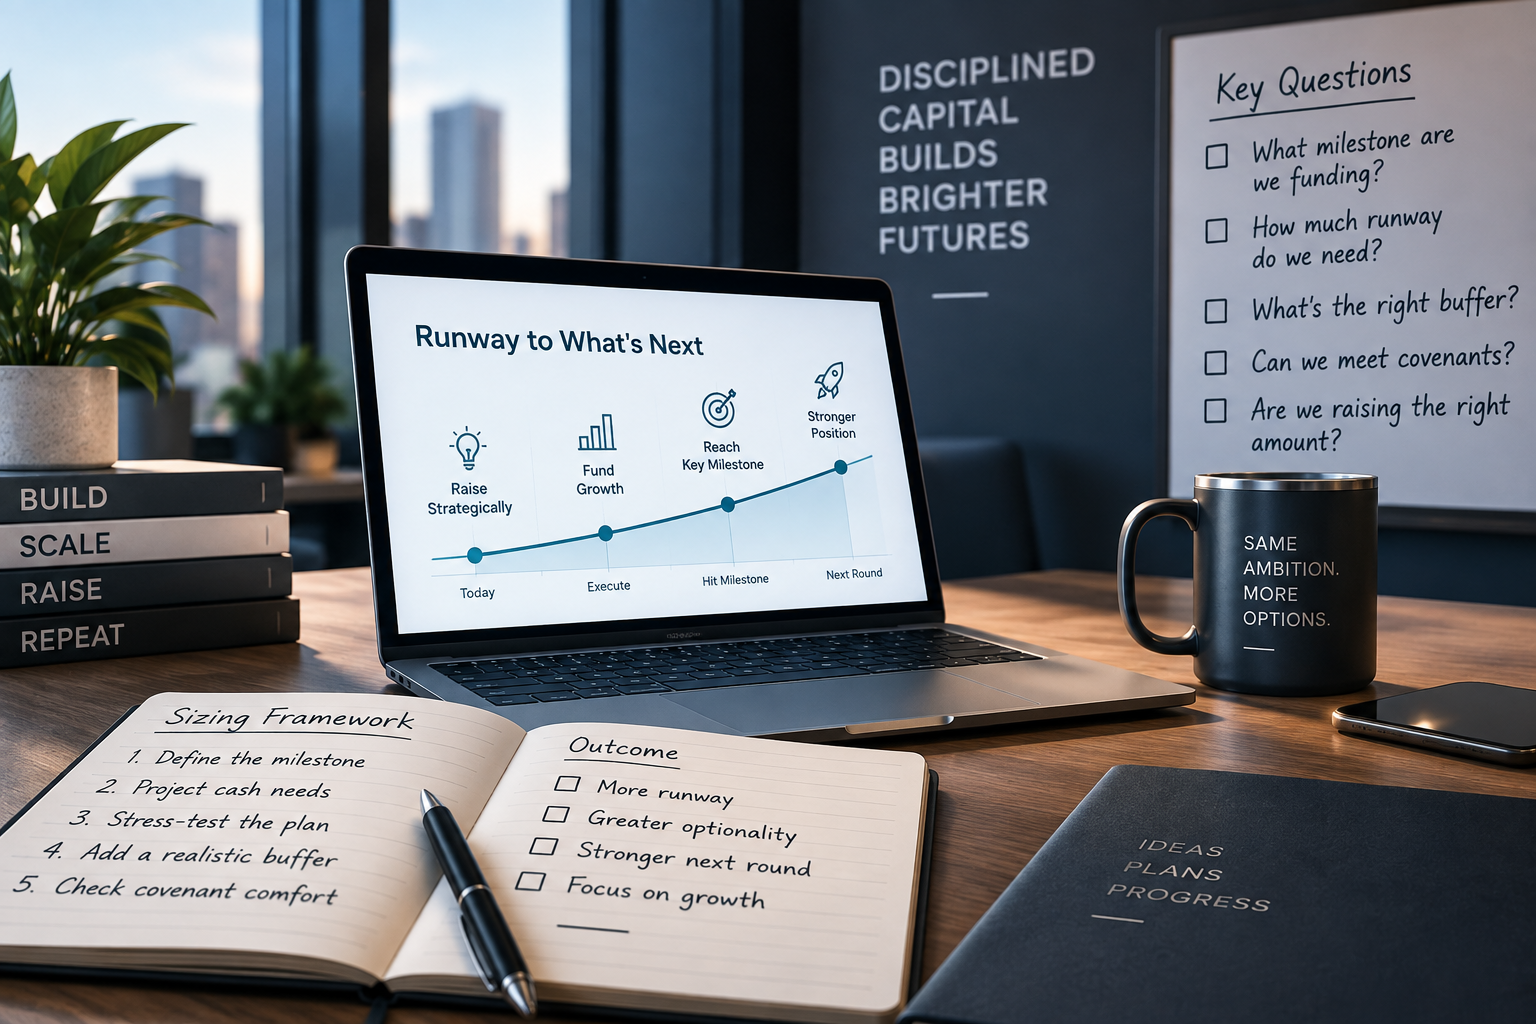
A practical sizing exercise
- Define the milestone you’re raising debt to reach, in specific, measurable terms.
- Project the cash needed to reach it under your current operating plan.
- Stress-test that projection against a more conservative revenue and expense scenario — what happens if growth is 20% slower than planned, or a key hire takes longer to make an impact?
- Add a buffer based on the gap between your best-case and conservative scenarios, not just your best case alone.
- Check covenant comfort under the conservative scenario, not just the plan you’re hoping for.
Why this is different from sizing an equity round
Equity investors often push for a larger round than a founder might otherwise choose, partly because more capital gives the company more room to pursue upside opportunities, and partly because the investor’s return is tied to company value rather than a fixed repayment amount. Venture debt doesn’t carry that same dynamic — the lender’s return is largely fixed regardless of how big your eventual outcome is, so there’s less external pressure to raise more than your actual milestone requires. That makes disciplined, milestone-based sizing both more possible and more valuable with debt than it typically is with equity.
What to do if you’re unsure
If you’re genuinely unsure whether you’re sizing a raise correctly, that uncertainty is worth surfacing directly with potential lenders rather than guessing. A good venture lending partner will engage with your actual milestone and cash flow projections, not just tell you the maximum amount your company could qualify for — and a lender pushing you toward a larger number than your own projections support is worth treating as a signal, not just an opportunity.
FAQ
Is it better to raise slightly more than I think I need, just in case? This depends on your specific covenant structure and cost tolerance — a modest buffer based on realistic downside scenarios is different from raising substantially more “just in case,” which carries real cost without a specific purpose behind it.
Can I raise additional venture debt later if my first raise turns out to be too small? Often yes, though terms for a subsequent raise depend on your company’s performance and market conditions at that time — which is exactly why realistic sizing on the first raise matters.
Should my milestone be based on my best-case plan or a conservative one? The milestone itself can reflect your genuine target, but the cash sizing to reach it should be stress-tested against a more conservative scenario, not just the plan you’re hoping plays out.