Taking on venture debt is rarely a company’s final financing event — for most venture-backed companies, it’s a bridge to a future equity round. Understanding how that existing debt is likely to be viewed by future equity investors helps you both structure the original debt more thoughtfully and present it well when the next raise comes around.
Why investors care about existing debt at all
An equity investor evaluating your company during due diligence will look at your full capital structure, including any outstanding venture debt — because it represents a senior claim on the company’s assets and cash flow ahead of equity holders, and because the terms of that debt (covenants, warrants, repayment obligations) can affect the company’s flexibility going forward, which matters directly to an investor’s own risk assessment.
How reasonable, well-structured venture debt is typically viewed
Used well, venture debt is generally viewed neutrally to positively by sophisticated investors — it signals the company had access to institutional debt, which itself reflects some validation of the business’s trajectory, and it shows the company extended its runway or funded a specific initiative without unnecessary dilution ahead of the round being raised. This is a very different story than debt that appears to have been used to cover a fundamental gap between the business’s plan and its actual performance.
What can make existing debt a point of concern in diligence
Aggressive covenants that meaningfully constrain the company’s operating flexibility, significant warrant coverage that represents real additional dilution beyond the equity being raised, or debt that appears to have funded ongoing operating losses rather than a specific, well-reasoned growth initiative can all raise more pointed questions during an equity round’s due diligence process.
How warrants specifically factor into the next round
Warrants attached to venture debt represent a dilution event that isn’t part of the current equity round being negotiated, but that does affect the overall cap table an incoming investor is evaluating. Being able to clearly account for warrant coverage — how much dilution it represents and under what terms it could be exercised — as part of your cap table presentation avoids this becoming an unclear or surprising element during diligence.
Presenting venture debt well in your next fundraising narrative
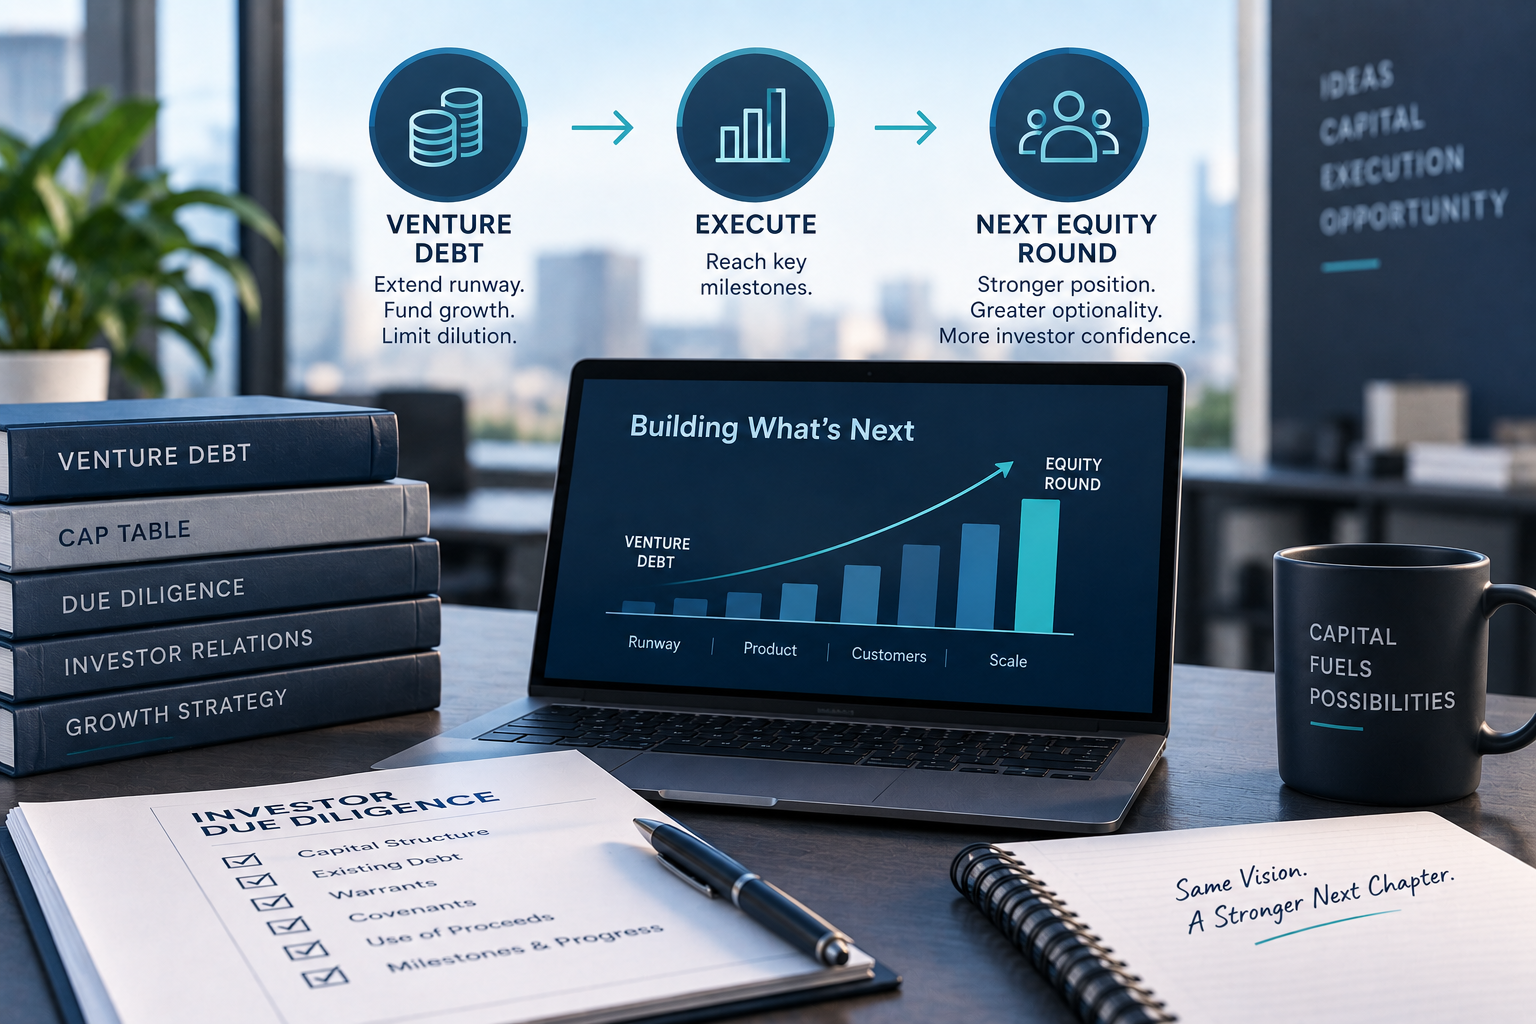
The most effective framing treats venture debt as a deliberate, milestone-oriented decision: what specific goal did the debt fund, what progress did it enable, and how did it support the company’s position heading into this round. Investors generally respond better to this clear, purposeful narrative than to a vague explanation, or to debt that appears to have been taken reactively without a specific plan behind it.
Why this is a reason to be disciplined about venture debt sizing upfront
This connects directly back to how much venture debt to raise in the first place: debt sized carefully against a specific, achievable milestone tends to support a cleaner story in your next round than debt raised more loosely, without a clear plan, that ends up looking — in hindsight, during due diligence — like it papered over a gap in the business’s trajectory rather than funding a deliberate initiative.
What to prepare before your next round if you have existing venture debt
Have a clear, concise summary ready: the amount outstanding, the key terms (interest rate, covenants, warrant coverage), what the capital was used for, and the progress that resulted from it. Presenting this proactively and clearly, rather than waiting for an investor to ask and piece it together themselves, tends to produce a smoother diligence process.
FAQ
Does having venture debt automatically lower my company’s valuation in the next round? Not automatically — well-structured, purposefully used venture debt is generally viewed as a normal part of a growth-stage company’s capital structure, rather than an inherent negative, though poorly structured or poorly explained debt can raise concerns.
Should I pay off venture debt before raising equity? Not necessarily — this depends on your specific terms, your cash position, and whether the debt is actively constraining your operations. It’s a decision worth evaluating deliberately rather than assuming it’s always better to be debt-free heading into a raise.
Do all equity investors scrutinize venture debt the same way? No — more experienced, growth-stage-focused investors are often quite familiar with venture debt as a standard tool and evaluate it based on how it was used, while less experienced investors may need more context and explanation.