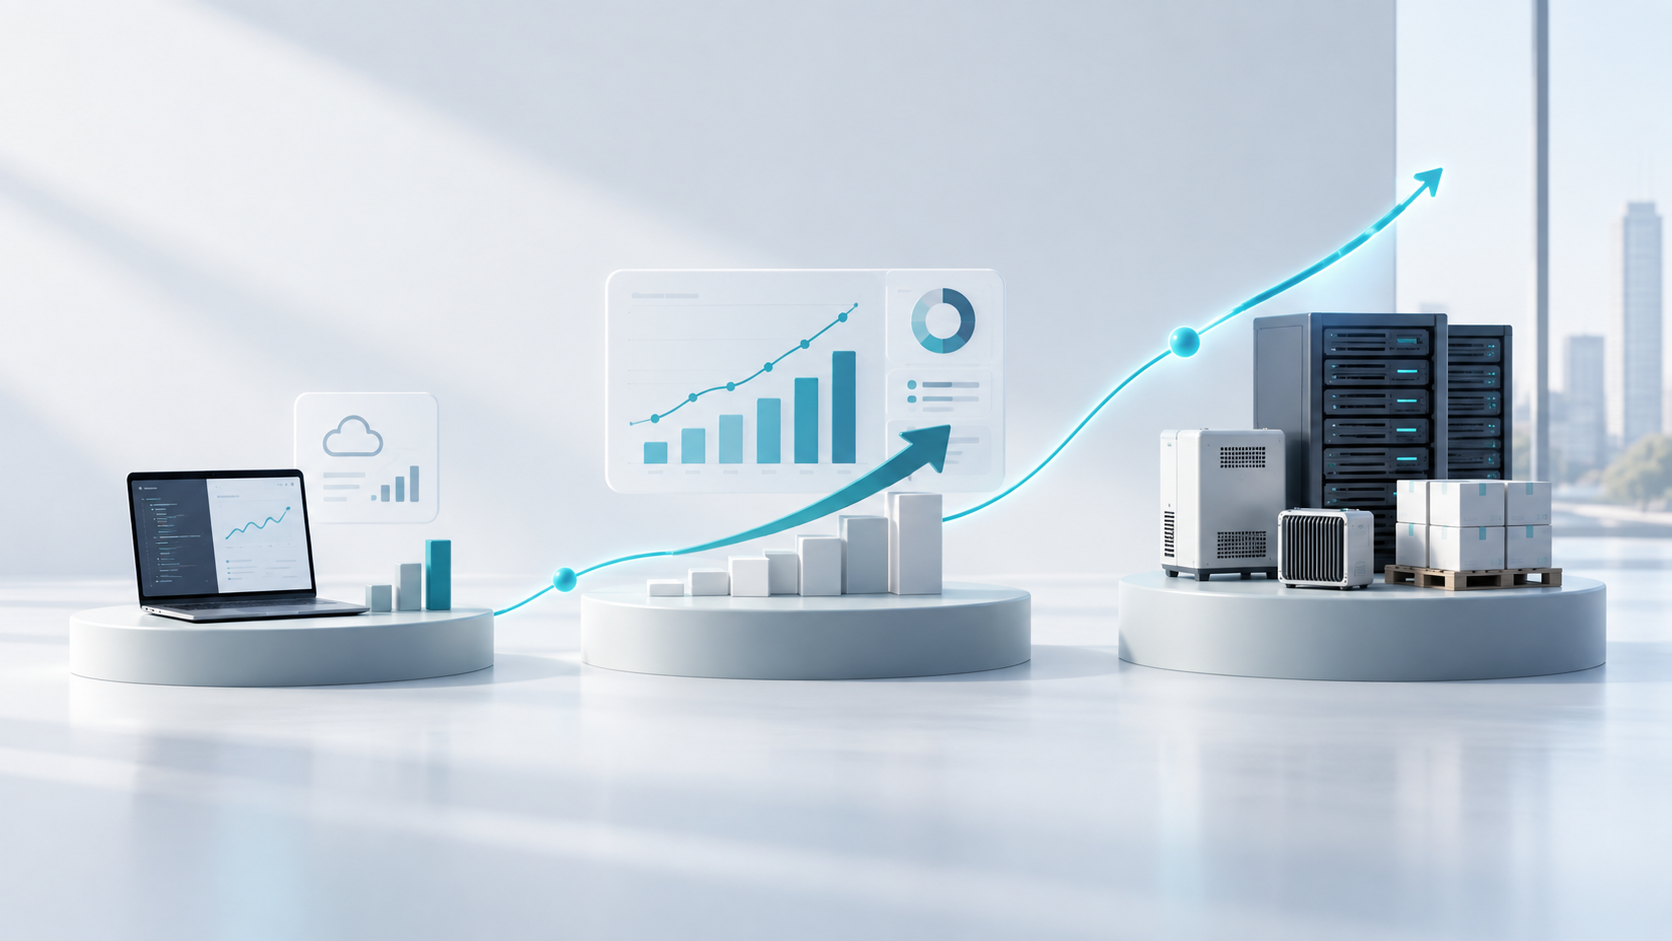
“Technology company” describes businesses at wildly different stages, with wildly different financing needs — a bootstrapped software company with steady revenue and no outside investors has almost nothing in common, financially, with a venture-backed startup three years from profitability. Yet both are often lumped into the same generic “startup funding” conversation. The more useful question isn’t “what funding do tech companies use,” but “what funding structure matches this specific company’s stage and revenue profile.”
Early revenue, no institutional backing
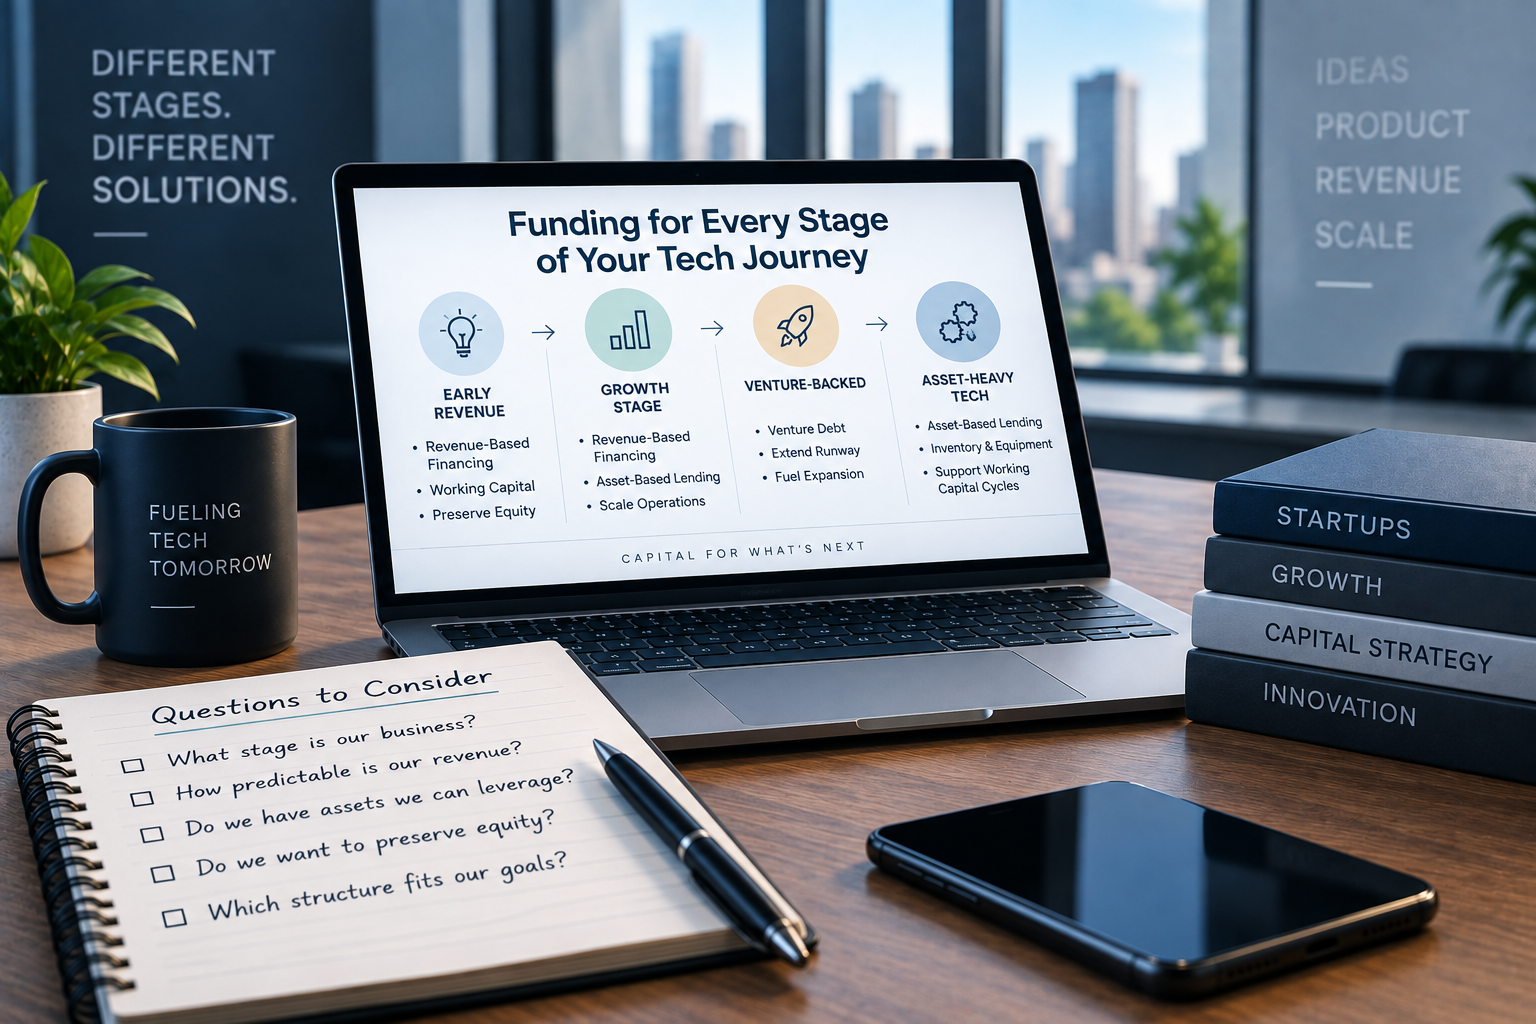
A technology company with real, growing revenue but no equity investors behind it often has more financing options available than founders initially assume — the absence of venture backing doesn’t disqualify a business from most financing types, since many structures are underwritten against revenue and business fundamentals rather than investor pedigree. Revenue-based financing tends to be a strong fit here: capital that scales with revenue, doesn’t require giving up equity, and doesn’t depend on having raised institutional funding in the first place.
Venture-backed, pre-profitability
For companies that have raised institutional equity and are prioritizing growth over near-term profitability, venture debt becomes a relevant option specifically because it’s underwritten with an understanding of that growth-stage profile — recognizing that the company’s equity backing and trajectory matter as much as current profitability. This is where the choice between raising more equity and taking on venture debt becomes most relevant, and where extending runway without further dilution often makes the most sense.
Asset-heavy technology businesses
Not every technology company is asset-light. Hardware companies, technology-enabled logistics businesses, and companies with significant equipment or inventory investments may be better served by asset-based lending than by financing structures built around software-style revenue models. It’s worth evaluating your business against its actual balance sheet, not just the “tech company” label, when considering which financing structure fits.
Technology companies with working capital cycles
Technology businesses that sell hardware, that resell software licenses with upfront cost commitments, or that operate on B2B invoicing with long payment terms face working capital dynamics closer to a traditional distribution business than a pure SaaS company. For these businesses, working capital lines of credit or invoice financing may be more relevant than the venture-focused products typically associated with “tech” funding conversations.
Why the generic “startup funding” conversation often leads companies astray
A significant amount of general startup funding advice assumes a venture-backed trajectory: raise a seed round, then a Series A, then Series B, and so on. That path fits a subset of technology companies well and fits a much larger group poorly — companies with real revenue and no interest in an eventual acquisition or IPO, for example, may be better served entirely outside that framework, using revenue-based financing or working capital structures instead of chasing an equity path that doesn’t match their actual goals.
Questions to ask about your own company before choosing a direction
- Does your growth depend on continuing to raise larger equity rounds, or could it be funded by debt against your own revenue or assets?
- Is your revenue recurring and predictable, seasonal, or transaction-based — and which financing structures actually match that pattern?
- Do you have meaningful physical assets, inventory, or receivables that could support asset-based lending, or is your balance sheet mostly intangible?
- Is your goal to preserve maximum ownership and control, or are you comfortable trading some of both for the resources a strong equity investor can bring?
Matching structure to stage isn’t a one-time decision
As a technology company grows, the right financing structure often changes. A company that used revenue-based financing in its early growth phase might be a strong venture debt candidate a few years later once it’s raised institutional equity — or might never need to make that shift at all, if its growth remains funded comfortably through revenue-based structures. Revisiting the question periodically, rather than assuming the first structure you used is the one your company will always use, tends to produce better outcomes over time.
FAQ
Do I need to choose between venture debt and revenue-based financing permanently? No — many technology companies use different structures at different stages, or even simultaneously for different purposes, rather than committing to one path indefinitely.
Does being a “tech company” automatically mean I should raise venture capital? No — this is one path among several, and it fits companies with a specific growth trajectory and investor-return orientation better than it fits companies with different goals, such as steady, founder-retained growth.
How do I know if my technology business is asset-light or asset-heavy for financing purposes? Look at your actual balance sheet: significant inventory, equipment, or hardware investment points toward asset-based structures being relevant, while a business built primarily on software and services with minimal physical assets points toward revenue-based or venture structures instead.