Revenue-based financing has a genuinely appealing pitch — flexible repayment, no equity given up, no fixed monthly obligation — which is exactly why it’s worth evaluating specific offers carefully rather than assuming every offer structured this way is equally fair. A flexible-sounding structure can still contain terms that work against your business. Here are five things worth checking closely before you sign.
1. No clear, written definition of “revenue”
If an offer doesn’t precisely define what counts as revenue for repayment purposes — gross revenue, net revenue, revenue excluding certain categories — that ambiguity can become a real problem later, particularly in a month with unusual activity. A fair offer defines this clearly and in writing, not verbally or vaguely. If you can’t get a precise answer to “exactly what counts as revenue here,” treat that as a warning sign, not a minor detail to sort out later.
2. A repayment percentage that doesn’t leave room to operate
Some offers set the revenue percentage aggressively high, on the assumption that a business will simply absorb it. But a percentage that doesn’t leave enough revenue to cover payroll, suppliers, and other operating costs in a normal month isn’t flexible — it’s just a fixed strain wearing a flexible-sounding label. Model your typical month’s revenue against the proposed percentage before agreeing to it, not after.
3. No minimum payment floor disclosure — or an aggressive one buried in the fine print
Many revenue-based structures include a minimum payment regardless of revenue in a given period, which is reasonable in principle. The red flag is when this isn’t clearly disclosed upfront, or when the minimum is set high enough that it effectively defeats the purpose of a revenue-scaling structure during a genuinely slow month. Ask directly whether a floor exists, what it is, and whether your slowest historical month would comfortably support it.
4. Prepayment penalties that discourage paying off the balance early
A structure that penalizes you for repaying faster than expected — even though faster repayment benefits the lender by reducing their risk exposure — suggests the offer is optimized to maximize the lender’s total return over the longest possible timeline, rather than to align with your business’s actual interests. Not every revenue-based offer includes this, but it’s worth checking explicitly rather than assuming early repayment is always beneficial or always penalty-free.
5. Vague or evasive answers about default triggers and remedies
If a sales conversation moves quickly past what happens in a genuinely bad scenario — sustained revenue decline, a missed payment, a covenant issue — and the written agreement is equally vague, that’s a meaningful gap. A transparent lender should be able to explain clearly, in plain language, exactly what happens if your business underperforms significantly relative to plan, and what options exist at that point. Reluctance to engage with this question directly is itself useful information.
Why these red flags matter more than the headline pitch
The appeal of revenue-based financing — flexibility, no fixed payment, no equity given up — is genuine when the structure is built fairly. But that same flexible framing can also be used to obscure less favorable terms, precisely because “it scales with your revenue” sounds inherently reasonable regardless of the specific percentage, floor, or definition involved. Evaluating the specific numbers and definitions in front of you matters more than trusting the general reputation of the financing category.
A practical pre-signing checklist
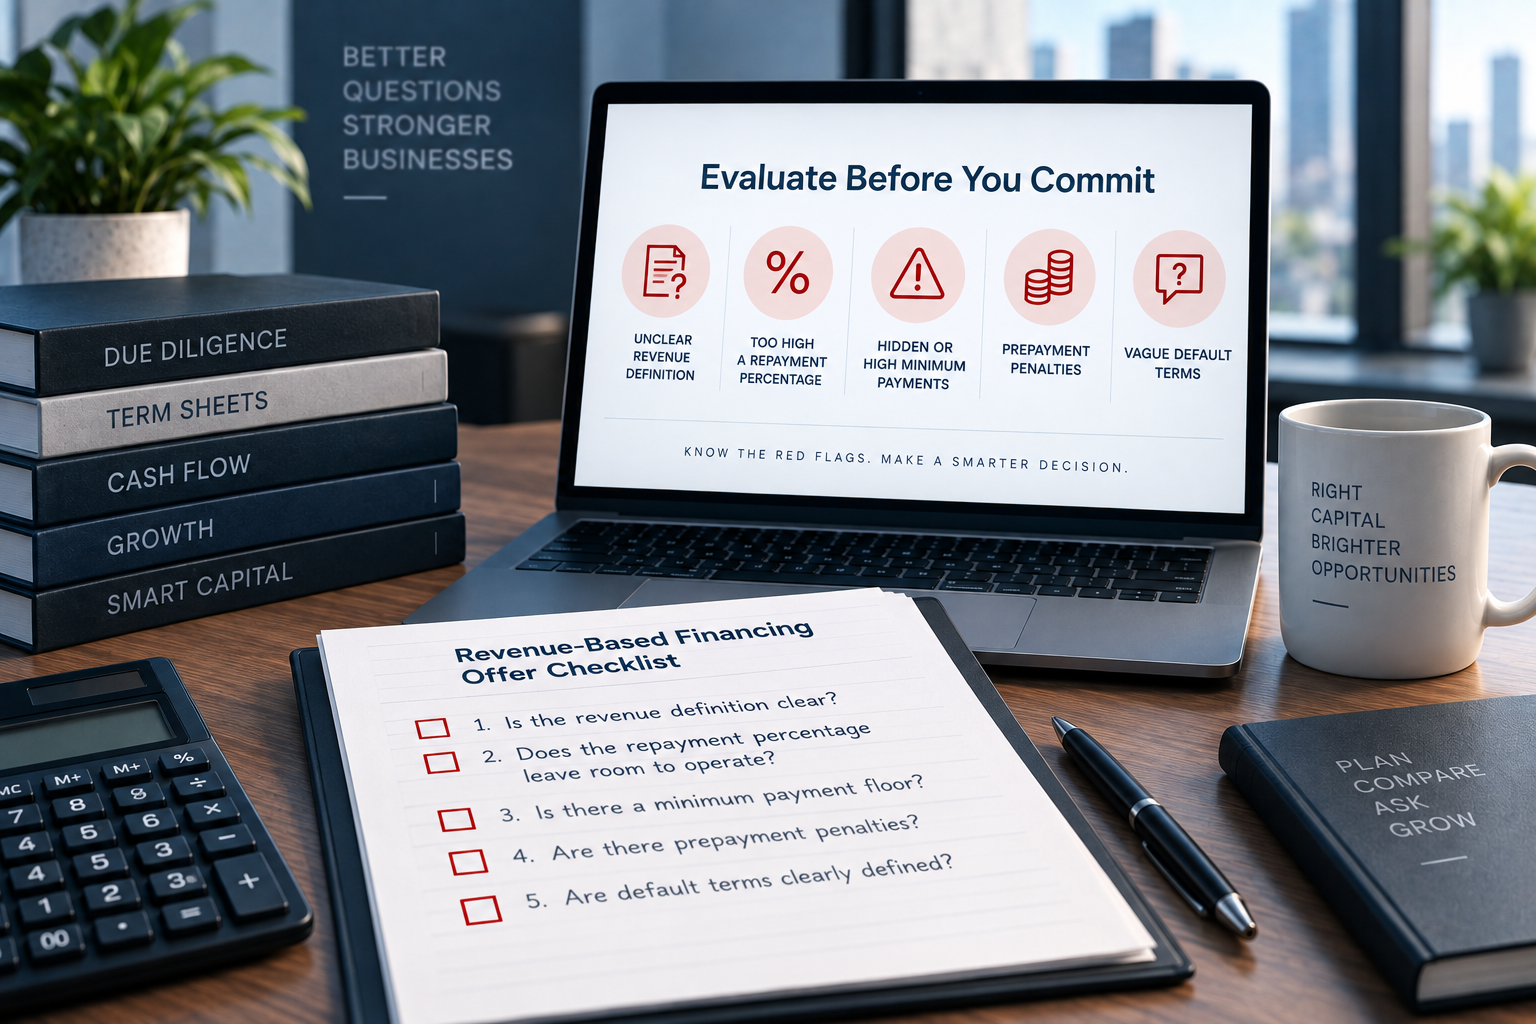
Before agreeing to any revenue-based financing offer, confirm in writing: the precise definition of revenue used for repayment, the percentage applied, whether a minimum payment floor exists and what it is, whether early repayment carries any penalty, and what specifically constitutes a default along with the consequences. If any of these five points can’t be answered clearly and in writing, that’s worth resolving before you sign — not after.
FAQ
Are all revenue-based financing offers structured unfairly? No — many are structured fairly and transparently. The point of this checklist isn’t to be suspicious of the category as a whole, but to evaluate the specific offer in front of you on its actual terms.
Is it reasonable to ask a lender to clarify these points in writing before signing? Yes, absolutely — this is standard due diligence, and a fair, transparent lender should have no issue providing clear written answers to all of these questions.
What if I’ve already signed an offer and I’m not sure it addressed these points clearly? It’s worth reviewing your existing agreement against this checklist directly, and if something is genuinely unclear, raising it with your lender rather than assuming the least favorable interpretation is automatically correct.